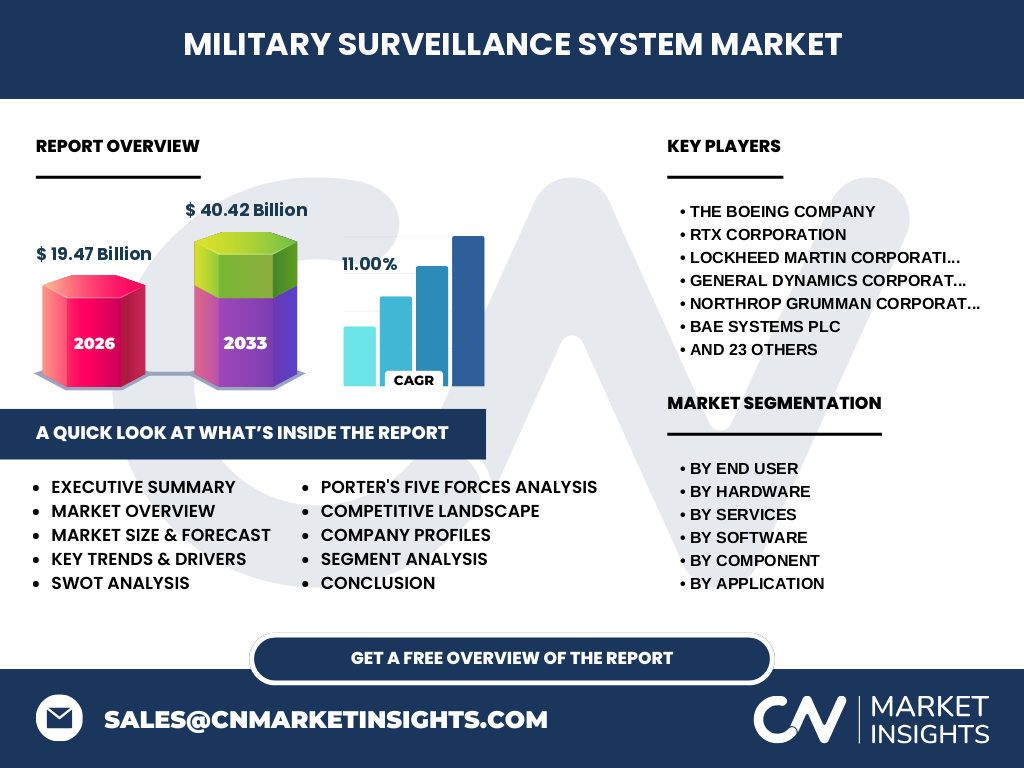
Market overview of the Military Surveillance System Market
Our analysis indicates that the Military Surveillance System Market is valued at 19.47 Billion in 2026. This sector encompasses advanced sensor systems, radar networks, and artificial intelligence monitoring platforms deployed globally by defense agencies to ensure absolute situational awareness across air, land, maritime, and cyber domains.
Key market drivers, restraints, challenges, and opportunities shaping the Military Surveillance System Market
Structural growth is heavily driven by rising geopolitical friction and the global race to modernize legacy Command and Control software. However, severe supply chain bottlenecks for gallium arsenide raw materials and strict ITAR export regulations act as persistent restraints, creating high barriers to entry for emerging defense tech contractors.
Emerging trends and growth patterns in the Military Surveillance System Market
The defense sector is undergoing a massive shift toward decentralized edge computing and multi-domain data fusion. Prime contractors like Palantir Technologies Inc. and Anduril Industries Inc. are leading this transition by integrating autonomous aerial platforms with real-time video management software to drastically reduce sensor-to-shooter latency.
COVID-19 impact analysis on the Military Surveillance System Market
While the pandemic initially crippled Tier-2 supply chains and delayed aerospace manufacturing schedules for firms like RTX Corporation, it ultimately accelerated government digital transformation budgets. Post-pandemic recovery has been robust, fueled by urgent national security mandates requiring touchless, AI-powered remote border surveillance nodes.
Competitive landscape and strategic dynamics of the Military Surveillance System Market
The industry features a bifurcated competitive landscape dominated by defense primes like Lockheed Martin Corporation, Northrop Grumman Corporation, and BAE Systems plc alongside agile disruptors. Market concentration remains high, forcing legacy primes into aggressive mergers and acquisitions to capture specialized cybersecurity software capabilities.
Executive summary of the Military Surveillance System Market
The data suggests the Military Surveillance System Market will expand from 19.47 Billion in 2026 to 40.42 Billion by 2033 at a CAGR of 11.00%. This explosive growth underscores an unprecedented global pivot toward autonomous reconnaissance, advanced radar modernization, and resilient intelligence collection architectures.
Market forecast from 2027 to 2033
Projected to scale rapidly from 2027 onward, the market will achieve a robust 11.00% CAGR, culminating in a total market valuation of 40.42 Billion by 2033. This trajectory is underpinned by multi-year defense spending bills targeting continuous surveillance network upgrades and space-based persistent intelligence assets.
Segmentation analysis across hardware, software, services, end users, and applications
Market segmentation spans critical categories: By End User (Army, Navy, Air Force, Homeland Security); By Hardware (Sensor, Imaging, Radar, Communication, Data Storage, Display); By Services (Installation, Maintenance, Training, Consulting, Managed); By Software (Analytics, Command & Control, Video Management, Data Fusion, Cybersecurity, AI Monitoring); By Component; and By Application (ISR, Border, Battlefield, Coastal Surveillance).
Regional market analysis and geographic distribution
North America dominates global consumption due to massive Pentagon outlays for multi-domain battle management networks. Meanwhile, the Asia-Pacific region represents the fastest-growing theater, driven by maritime territorial disputes in the South China Sea that necessitate heavy investments in coastal radar systems and advanced intelligence architectures.
In-depth regional review of key deployment zones
European defense modernization programs, coordinated through the European Defence Agency, prioritize sovereign intelligence capabilities and robust cybersecurity software integration. Simultaneously, Middle Eastern nations continue heavy capital allocation toward border surveillance and persistent aerial reconnaissance systems procured through prime foreign military sales channels.
Company profiles and strategic positioning of leading market participants
Industry leaders like General Dynamics Corporation, Thales S.A., Leonardo S.p.A., and L3Harris Technologies Inc. anchor their strategies in turnkey prime contracting. Meanwhile, specialized innovators such as Teledyne FLIR LLC and HENSOLDT AG focus on high-precision optical hardware and advanced electronic warfare sensors to maintain pricing power.
Porter's Five Forces analysis of competitive pressures
The threat of new entrants remains constrained by extreme capital requirements, stringent security clearances, and military certification hurdles. However, buyer power is moderately high given that sovereign defense ministries dictate procurement terms, while supplier power concentrates tightly around high-purity semiconductor and specialized optical component vendors.
SWOT analysis of the Military Surveillance System Market
Strengths include unmatched technological precision and deep government backing. Weaknesses involve sluggish bureaucratic procurement cycles. Opportunities lie in commercial-off-the-shelf dual-use AI integration. Threats center on geopolitical trade restrictions and cyber-attacks targeting proprietary data fusion algorithms.
Value chain analysis from raw materials to end-users
The value chain originates with rare-earth mineral mining and semiconductor fabrication, flowing into subsystem manufacturing by firms like Safran S.A. and Saab Aktiebolag. System integration by prime contractors yields finished command and control nodes delivered directly to armed forces end-users.
Investment insights and strategic recommendations
Investors should target pure-play artificial intelligence monitoring software providers and commercial space-intelligence innovators like Planet Labs PBC, BlackSky Technology Inc., and HawkEye 360 Inc. These entities offer high-margin scalability that traditional heavy hardware manufacturers cannot easily replicate.
Conclusion and key takeaways for stakeholders
Reaching 40.42 Billion by 2033, the market rewards enterprises capable of merging ruggedized hardware with software-defined intelligence. Stakeholders must prioritize open architecture compliance to secure long-term defense modernization contracts across global allied nations.
Research methodology for baseline estimation and data triangulation
Our baseline estimates are rigorously triangulated by cross-referencing national defense budget allocations, trade registry data, and primary qualitative interviews with C-level executives from firms like Kratos Defense & Security Solutions and TCOM L.P., validated against macroeconomic indicators.
Scope of the report and coverage parameters
This comprehensive report covers global deployment trends, hardware innovations, and software integrations from 2026 through 2033. It excludes classified black-budget defense programs lacking verifiable public procurement data, focusing exclusively on addressable commercial and unclassified military surveillance markets.
Recent developments in partnerships, product launches, and strategic moves
Recent milestones include General Atomics Aeronautical Systems Inc. deploying advanced long-endurance drone sensors, and strategic partnerships forged between traditional primes and agile software firms to accelerate Department of Defense Joint All-Domain Command and Control initiatives globally.